News & Insights

Insights

Understanding LCA and EPD Impact Categories

In this article, our LCA Consultant Helen Brown takes us on a tour of three major LCA and EPD impact category sets; EF 3.1, ReCiPe 2016 and EN15804+A2. This covers the details of each set and within this the definitions of each category, what they assess and how to interpret the resulting values. 

What are Impact Categories? 

The primary objective of the use of impact categories is to translate emissions and resource extractions into a modest number of environmental impact scores. These scores express the severity of the environmental impact within a specific impact category and can be used to quantify a product’s or process’s impact on the environment. 

They are simply factors to multiply something by, to give the environmental impact. For example, if we are looking at climate change, we could consider 20 year Global Warming Potential. For methane, the factor for this impact category is 86kgCO2e/kg1. Therefore, the way this would work for 10kg of methane would be. 

Amount of material x factor = impact 

10kg methane x 86kgCO2e/kg = 860 kgCO2e 

When selecting impact categories, the integrative concept of sustainable development is taken as a normative framework for identifying the sustainability criteria appropriate for product being studied. Based on this concept, a certain set of impact categories is included per project. The impact categories that your product’s environmental impacts are displayed in will be defined in the goal and scope document for the LCA or EPD. 

Midpoints and Endpoints 

Before we begin, we must understand impact category terminology. Midpoint impact categories cover single environmental issues, such as global warming or water use. These feed through damage pathways into three endpoint areas: human health, ecosystems and resource availability. Endpoint results are usually easier to interpret, but that simplicity comes at a cost as this broader modelling carries more uncertainty. 

ReCiPe 2016 

Most impact category methods focus only on midpoint indicators. In contrast, the ReCiPe method ​(Huijbregts et al., 2016)​, which is a follow-up of Eco-indicator 99 and CML 2002 methods, integrates and harmonises midpoint and endpoint approach in a consistent framework ​(Margni & Curran, 2012)​.  This approach is made up of 18 midpoint categories and 3 endpoint categories. An illustrative example of how midpoints feed into endpoint categories within this methodology can be found in Figure 1.  

ReCiPe 2016 also employs three different assessment perspectives, the most popular being Hierarchist (H) which sits between the two extremes: 

  • Individualist (I) represents a short time situation where technology can solve many problems and considers only proven effects. 
  • Hierarchist (H) is a balance between long and short term, in a situation where it is believed that policy can avoid many problems which considers effects based on consensus. 
  • Egalitarian (E) represents a very long-term situation where problems lead to catastrophe which considers all possible side effects. 

ReCiPe 2016 Impact Categories 

Figure 1. Overview of the impact categories that are covered in the ReCiPe2016 methodology and their relation to the areas of protection (Huijbregts, et al., 2016) 
  • Global warming (GWP100) – The product’s contribution to climate change over a 100 year horizon. This is the figure most people mean by a carbon footprint. 
  • Stratospheric ozone depletion (ODP) – Damage to the high-altitude ozone layer that shields us from UV radiation, driven mainly by refrigerants, foam blowing agents and older solvents. 
  • Ionising radiation (IRP) – The human health risk from radioactive releases across the life cycle, expressed relative to cobalt-60. Grid electricity is often the largest source. 
  • Ozone formation, human health (HOFP) – Ground-level ozone, the summer smog that forms when volatile organic compounds react with nitrogen oxides in sunlight, assessed for its effect on people’s lungs. 
  • Fine particulate matter formation (PMFP) – The potential for emissions to form fine airborne particles small enough to be drawn deep into the lungs. 
  • Ozone formation, terrestrial ecosystems (EOFP) – The same ground-level ozone, this time assessed for the damage it does to plants and crops rather than to people. 
  • Terrestrial acidification (TAP) – Acidification of soils by sulphur dioxide, nitrogen oxides and ammonia, which can damage plant life and forests. 
  • Freshwater eutrophication (FEP) – Phosphorus reaching rivers and lakes, where it over-feeds algae and triggers blooms that strip the water of oxygen. 
  • Marine eutrophication (MEP) – Nitrogen reaching coastal and marine waters, driving the same algal bloom and oxygen-loss problems at sea. 
  • Terrestrial ecotoxicity (TETP) – Harm to soil-dwelling organisms from toxic substances released to land. 
  • Freshwater ecotoxicity (FETP) – Harm to plants and animals in rivers and lakes from toxic substances released. 
  • Marine ecotoxicity (METP) – Harm to plants and animals in seas and oceans from toxic substances released. 
  • Human carcinogenic toxicity (HTPc) – The potential for the product’s emissions to cause cancer through exposure via air, water or soil. 
  • Human non-carcinogenic toxicity (HTPnc) – The potential for emissions to cause non-cancer harm, such as organ damage or respiratory illness. 
  • Land use (LOP) – How much land the supply chain occupies or transforms, and for how long, reflecting the natural land lost as a result. ReCiPe 2016 folds the older separate farmland, urban land and land-transformation measures into this single indicator. 
  • Mineral resource scarcity (SOP) – How far the life cycle draws down finite metal and mineral ores, expressed relative to copper. A high figure points to reliance on scarcer or lower-grade ores. 
  • Fossil resource scarcity (FFP) – How much oil, gas and coal the life cycle uses up, expressed as an equivalent mass of crude oil. 
  • Water consumption (WCP) – The net volume of freshwater consumed and not returned to its source. 

Environmental Footprint (EF) 3.1 

The Environmental Footprint method (EF 3.1) (European Commission Joint Research Centre, 2022; Andreasi Bassi et al., 2023) was developed by the European Commission’s Joint Research Centre to standardise Product and Organisation Environmental Footprint studies across the EU (European Commission, 2021). The method operates exclusively at midpoint level, without a modelled endpoint stage (Fazio et al., 2018). It comprises 16 impact categories, several of which are split into the sub-indicators listed below. 

EF 3.1 Impact Categories 

  • Acidification – Measures a product’s contribution to acid rain and acid deposition. Emissions (mainly SO₂, NOx and ammonia) react in the atmosphere and fall back to earth as acids, damaging soil, freshwater ecosystems, forests and building materials. 
  • Climate change – The product’s contribution to climate change over a 100 year horizon, and the figure most people mean by a carbon footprint. 
  • Climate change: biogenic – The share of the carbon footprint from biological sources, such as CO2 released when wood, plant fibres or other organic material decomposes or is burnt. 
  • Climate change: fossil – The share of the carbon footprint from fossil sources: burning coal, oil and gas, or the fossil carbon locked into materials such as plastics. For most manufactured products this is the dominant contributor. 
  • Climate change: land use and land use change – The share of the carbon footprint caused by converting land from one use to another, for example clearing forest for agriculture or development, which releases carbon previously stored in soil and vegetation. 
  • Ecotoxicity: freshwater – The potential harm to plants and animals living in rivers and lakes from toxic substances released. 
  • Ecotoxicity: freshwater, inorganics – The share of freshwater ecotoxicity caused by inorganic substances, mainly metals released to water or soil, for example from mining, metal processing or corrosion. 
  • Ecotoxicity: freshwater, organics – The share of freshwater ecotoxicity caused by organic chemicals, such as solvents, pesticides or chemical processing aids. 
  • Energy resources: non-renewable – Measures how much non-renewable energy, from fossil fuels and uranium, is used up in making a product. 
  • Eutrophication: freshwater – The amount of phosphorus reaching freshwater. Phosphorus over-feeds algae, causing blooms that starve the water of oxygen and harm fish and other aquatic life. 
  • Eutrophication: marine – The amount of nitrogen released that can end up in marine waters, driving algal bloom and oxygen-loss problems in coastal and marine settings. 
  • Eutrophication: terrestrial – Assesses nutrient enrichment on land caused by excess nitrogen, mainly from ammonia and NOx emissions. Excess nitrogen changes soil chemistry and can reduce plant biodiversity. 
  • Human toxicity: carcinogenic – The potential for a product’s emissions, across its life cycle, to cause cancer in people, whether workers, nearby communities or end users. 
  • Human toxicity: carcinogenic, inorganics – The cancer-related share of human toxicity caused by inorganic substances, mainly metals. 
  • Human toxicity: carcinogenic, organics – The cancer-related share of human toxicity caused by organic chemicals. 
  • Human toxicity: non-carcinogenic – The potential for a product’s emissions to cause non-cancer health effects, such as organ damage, respiratory illness or reproductive harm. 
  • Human toxicity: non-carcinogenic, inorganics – The non-cancer share of human toxicity caused by inorganic substances, mainly metals. 
  • Human toxicity: non-carcinogenic, organics – The non-cancer share of human toxicity caused by organic chemicals. 
  • Ionising radiation: human health – The health risk to people from radioactive emissions across a product’s life cycle, most significantly linked to nuclear power feeding into the electricity supply used in manufacturing. 
  • Land use – The impact of occupying and changing land on soil quality, covering the soil’s ability to support plant growth, resist erosion, filter water and recharge groundwater. 
  • Material resources: metals/minerals – Measures how much a product depletes finite mineral and metal reserves, weighted by how scarce each resource is relative to antimony, the reference substance. 
  • Ozone depletion – The potential to damage the stratospheric ozone layer (which shields us from UV radiation) mainly relevant where refrigerants, foam blowing agents or older solvents are involved. 
  • Particulate matter formation – The potential for emissions to form fine airborne particles small enough to be inhaled deep into the lungs. 
  • Photochemical oxidant formation – The potential to create ground-level ozone (like summer smog), which forms when volatile organic compounds react with nitrogen oxides in sunlight. Unlike the stratospheric ozone layer, which protects us, ground-level ozone is a pollutant that irritates the lungs and damages crops. 
  • Water use – The net volume of water consumed (used and not returned to the source), reflecting pressure the product places on freshwater availability. 

EN 15804+A2 

EN 15804:2012+A2:2019 (CEN, 2019) is the European standard that sets the core product category rules for Environmental Product Declarations of construction products, defining how life cycle data is collected, assessed and reported across the product’s cradle-to-grave stages. The standard was amended in 2019 to bring its impact assessment in line with the European Commission’s Environmental Footprint method, replacing the seven impact categories of the earlier EN 15804+A1 with a set of indicators adopted from EF 3.1. EN 15804+A2 mandates 13 core environmental indicators and adds six further additional indicators alongside a supplementary indicator, for comparability with carbon-accounting frameworks. 

EN 15804+A2 Impact Categories 

Core Environmental Indicators 

  • Climate change – total (GWP-total) – The product’s overall contribution to global warming, combining fossil, biogenic and land-use-related greenhouse gas emissions into one figure. It is the sum of the three sub-indicators below and is usually the headline carbon footprint figure. 
  • Climate change – fossil (GWP-fossil) – The part of the footprint from fossil carbon: coal, oil and gas burnt for energy, plus the fossil carbon built into materials such as plastics. For most products this dominates the total. 
  • Climate change – biogenic (GWP-biogenic) – The share of the carbon footprint from biological sources, such as CO2 released when wood, plant fibres or other organic material decomposes or is burnt. EN 15804+A2 requires biogenic carbon in both the product and its packaging to be reported separately. 
  • Climate change – land use and land use change (GWP-luluc) – The part of the footprint from changing how land is used, such as clearing forest for farming or building, which releases carbon that soils and vegetation had stored. 
  • Ozone depletion (ODP) – Captures damage to the high-altitude ozone layer that filters out UV radiation. The usual sources are refrigerants, foam blowing agents and a few older solvents. 
  • Acidification potential (AP) – The product’s share of acid rain. Sulphur dioxide, nitrogen oxides and ammonia turn to acids in the air and fall back to earth, harming soils, freshwaters, forests and buildings. 
  • Eutrophication potential – freshwater (EP-freshwater) – Assesses a product’s contribution to nutrient pollution in lakes and rivers, driven by phosphorus. Excess phosphorus fuels algal blooms, which strip oxygen from the water and harm aquatic life. 
  • Eutrophication potential – marine (EP-marine) – The product’s contribution to nutrient pollution in seas and coastal waters, driven by nitrogen. The excess nitrogen fuels algal blooms that strip oxygen from the water and harm marine life. 
  • Eutrophication potential – terrestrial (EP-terrestrial) – Nutrient enrichment of land, mainly from ammonia and nitrogen oxides. The added nitrogen shifts soil chemistry and can crowd out less competitive plants, lowering biodiversity. 
  • Photochemical ozone formation (POCP) – Ground-level ozone, the main ingredient of summer smog, formed when volatile organic compounds meet nitrogen oxides in sunlight. At ground level ozone irritates the lungs and damages crops. 
  • Depletion of abiotic resources – minerals and metals (ADP-minerals&metals) – How far the product draws down finite mineral and metal reserves, each weighted by scarcity against the antimony benchmark. 
  • Depletion of abiotic resources – fossil fuels (ADP-fossil) – Measures how much non-renewable fossil energy, coal, oil and gas, is used up in making a product. 
  • Water use (WDP) – Net freshwater taken and not returned to source, a measure of the pressure the product places on water availability. 

Additional Mandatory Indicators 

EN 15804+A2 introduced these six indicators alongside the core set, covering human health and land use effects not captured above. The standard itself treats them as mandatory for the background LCA report and optional for the EPD document, flagging them as lower robustness than the core set; many programme operators however (including the International EPD System) now require them in the published EPD. 

  • Particulate matter emissions (PM) – The formation of fine airborne particles small enough to reach deep into the lungs. 
  • Ionising radiation – human health (IRP) – The human health risk from radioactive releases over the life cycle, usually traced back to nuclear power in the electricity used for manufacturing. 
  • Ecotoxicity – freshwater (ETP-fw) – Harm to life in rivers and lakes from toxic releases, spanning both organic chemicals and inorganic substances such as metals. 
  • Human toxicity – cancer effects (HTP-c) – The potential for life-cycle emissions to cause cancer, whether in workers, neighbouring communities or the people using the product. 
  • Human toxicity – non-cancer effects (HTP-nc) – The potential for emissions to cause non-cancer harm, such as organ damage, respiratory illness or reproductive effects. 
  • Soil quality (SQP) – The effect of occupying and altering land on soil, covering its capacity to grow plants, resist erosion, filter water and recharge groundwater. 
  1. Supplementary Indicator 

EN 15804+A2 adds a single, supplementary indicator so that EN 15804+A2 results can be compared against carbon-accounting frameworks that exclude biogenic carbon by convention, such as some corporate GHG inventories. 

  • Climate change – excluding biogenic carbon (GWP-GHG) – A voluntary indicator, required by some PCRs, that is calculated identically to GWP-total except that the characterisation factor for biogenic CO2 is set to zero. This removes the uptake and release of biogenic CO2 from the figure while keeping fossil emissions, land-use change emissions and non-CO2 biogenic gases (such as methane) in the total.  

Which Impact Category Should I Use? 

These three methodologies share the same underlying environmental science, but they diverge in the specific categories used and the methodologies used to calculate them. ReCiPe 2016 goes furthest, carrying midpoint results through to three endpoint areas so a product’s damage to human health, ecosystems and resource availability can be read on a single scale. EF 3.1 stops at midpoint level, but its harmonised category set now forms the backbone of EU environmental footprint policy. EN15804+A2 narrows the scope further still, borrowing EF 3.1’s indicators but applying them specifically to construction products, with several mandatory indicators and six more recommended by most programme operators. Which set applies to a given LCA or EPD comes down to the standard the study follows, a decision fixed at the outset in the project’s goal and scope document. 

How Below280 Can Help 

Below280 works with manufacturers and suppliers to pin down which of these three sets applies to their product carrying out fully ISO 14040/14044 compliant LCAs and EN 15804 EPDs itself, from goal and scope through to the final verified declaration. Get in touch with the team to discuss your project’s requirements.

Need help choosing the right EPD impact categories?

We pin down which methodology applies to your product and manage the full process, from goal and scope through to the final verified declaration.


Global commercial consultancy • Horizon Europe, UKRI & Innovate UK research partner. Specialists in openLCA, and UK openLCA partner for GreenDelta.

News

How to Drive Supplier Engagement for Reliable Sustainability Data Collection

There are growing pressures on businesses to take sustainability seriously across their products and supply chains. Your clients or investors may be pushing for a genuine sustainability agenda. Regulations like the EU’s ESPR may be imposing requirements on the sustainable design of your products. CBAM may be requiring you to account for the carbon embedded in products you import or export to the EU. Or your own leadership team may have set decarbonisation targets that require a clear baseline. Whatever the driver, there is a good chance you will need to commission an LCA study, produce an EPD, or calculate embedded emissions for CBAM compliance, all of which rely on reliable, representative environmental data for your products.

To get figures that genuinely reflect your product (rather than relying on generic industry averages or, in the case of CBAM, punitive default emission values), you need actual data from your supply chain. That means engaging your suppliers: understanding their processes, collecting their production data, and building the kind of relationship where that information flows reliably.

This is where most companies hit a wall. The instinct is to send a questionnaire, ask for energy consumption, material compositions, and waste data, then wait. What comes back is often incomplete, inconsistent, or nothing at all. The supplier does not understand what is being asked, does not see why it matters to them, or simply does not have the data in the format you need.

This is not a supplier problem. It is an engagement problem. The quality of the data you receive is directly tied to the quality of the relationship behind it. This guide explains how to approach supplier engagement in a way that delivers the data you need for LCA, EPD, and CBAM work, while building relationships that continue to pay off well beyond a single assessment.

Contents

  1. Why primary data matters for LCAs, EPDs & CBAM
  2. Why most supplier surveys fail
  3. Map what you already know
  4. Prioritise your suppliers strategically
  5. Approach suppliers as partners, not data sources
  6. Make requests specific, simple, and worthwhile
  7. Build trust through transparency
  8. Think long-term, not transactional
  9. From better data to better decisions
  10. The big picture: moving toward sustainable supply chain management
  11. FAQs

Why primary data matters for LCAs, EPDs & CBAM #

An LCA model typically uses a mix of primary and secondary data. Secondary data is sourced from online databases such as ecoinvent, LCA Commons, or Agribalyse, representing generic averages compiled from multiple geographically dispersed facilities, technologies, and time periods. Primary data, on the other hand, is measured directly from your own foreground processes and collected from your suppliers on their operations. When a supplier provides their actual electricity consumption per tonne of output, their specific material composition, or the real transport route from their facility to yours, the model shifts from a generic estimate to a reflection of your actual supply chain.

The balance between primary and secondary data affects model reliability and the certainty of the conclusions you can draw from it. A model built heavily on secondary data may not reflect the actual environmental footprint of your specific product, risking unreliable decisions about where to focus improvements. For EPDs, PCRs (within standards such as EN 15804) generally require primary data for foreground processes under the manufacturer’s control, and verifiers check that the declared product’s foreground is represented by that primary data rather than generic data. For CBAM, installation-specific emissions data for precursor materials is required, and if your supplier cannot provide it, your importer must use default values that are almost always higher than reality.

In each case, the accuracy of the data from your supply chain directly affects the credibility and commercial value of the assessment. Given time and feasibility constraints, however, not every process needs primary data from day one. The practical starting point is to identify where emissions are expected to concentrate and prioritise supplier data collection there first.

The accuracy of the data from your supply chain directly affects the credibility and commercial value of the assessment.

Back to top

Why most supplier surveys fail #

Data requested from suppliers can sometimes turn out to be of worse quality than the secondary data already available from databases, especially when the request is poorly designed or the relationship behind it is weak. Research backs this up. A study by Miah et al. (2017), which documented Nestle’s experience of collecting LCI data from 67 ingredients and packaging suppliers, found that only 55% returned the questionnaire. Critically, the study found that the level of supplier participation depended largely on trust and the strength of existing relationships. The reasons behind low response rates, both in that study and in wider practice, tend to follow a common pattern.

No context. The supplier receives a data request with no explanation of what it feeds into or what happens next. Without that context, the request simply gets deprioritised in favour of more pressing demands.

Too broad or too technical. Asking for data across an entire product range overwhelms the supplier, and using LCA-specific terminology without explanation makes it harder still. For many suppliers, particularly SMEs, completing an LCI questionnaire to the required level of detail is either a completely new exercise or one presented in unfamiliar technical language.

Commercial sensitivity. Suppliers may be reluctant to share production data for fear of it being used against them commercially. Despite reassurances such as non-disclosure agreements, resistance from some suppliers still remains.

No clear benefit. The supplier sees the effort required and no return. They are giving you something valuable and receiving nothing in exchange.

Survey fatigue and capacity gaps. Suppliers serving multiple customers receive sustainability questionnaires in different formats, each asking for slightly different things. Many, particularly SMEs, simply do not have the internal systems or expertise to respond accurately.

One-off framing. The request arrives as a one-time project, and because there is no ongoing relationship or expectation attached to it, the supplier puts it at the bottom of the pile.

The data usually exists somewhere in the supplier’s utility bills, production records, and purchasing systems. The challenge is creating the conditions in which they are willing and able to share it.

The data usually exists somewhere in the supplier’s records. The challenge is creating the conditions in which they’re willing to share it.

Back to top

Map what you already know #

Before approaching any of your suppliers, start by understanding what information you already have access to internally. Apart from the data you control directly from your own facility, including energy use, production volumes, scrap rates, waste streams, and transport records, this process involves reviewing all of your supplier-related purchasing information: what you buy, in what quantities, who supplies it, and how much it costs. This is your bill of materials, and it provides the foundation for approaching suppliers with confidence, demonstrating competence and respect for their time.

Once you have gathered this information, the next step is to run a screening assessment to identify potential hotspots for environmental impact. If your organisation already conducts carbon emissions reporting, the figures calculated for purchased goods and services under Scope 3 using spend or industry-average data may already highlight hotspots in your supply base. Alternatively, you can run an initial screening LCA using proxy data from LCA databases to estimate where environmental impacts are concentrated upstream in your supply chain. For most manufactured products, a small number of input materials account for the majority of the impact, and identifying those hotspots before engaging any suppliers ensures your efforts are targeted where they will make the biggest difference to the accuracy of your LCA model, EPD, or CBAM calculations.

Your bill of materials is the foundation for approaching suppliers with confidence.

Back to top

Prioritise your suppliers strategically #

From the results of the screening assessment, you will have a clearer picture of where to narrow down your focus. However, you do not need data from every supplier identified on day one. Engaging them all simultaneously leads to shallow engagement and poor quality data. The aim, instead, is to start building trust with a focused group of key suppliers, ensuring you get reliable, timely data while laying the groundwork for closer collaboration over time.

Selecting the top 5 to 10 suppliers identified in your screening process is a sensible starting point, as these typically account for the majority of your purchased goods’ environmental footprint. Getting the engagement right with those relationships first allows you to learn what works, what does not, and where gaps still remain, before expanding the exercise to reach others.

A significant portion of your spend on materials might also be coming from relatively low-carbon sectors, however, which is why screening for potential high-emitters across your supply base, such as metals, chemicals, or energy-intensive processing, is just as important. These materials can be disproportionately impactful even when they represent a smaller share of your total spend.

It is also worth noting that smaller suppliers with fewer competing demands can sometimes be easier to engage with initially and more eager for potential collaboration than the larger ones, who may already be fielding many similar requests. Tailoring requests to a larger supplier might therefore require more effort and time to get engagement started in the first place.

The screening assessment ultimately gives you the evidence base for making these decisions. Rather than guessing, you can point to the data and say: these five materials account for 80% of our product’s carbon footprint, and these are the suppliers we need to talk to first.

These five materials account for 80% of our product’s carbon footprint, and these are the suppliers we need to talk to first.

Back to top

Approach suppliers as partners, not data sources #

Getting in touch with a supplier for the first time and simply asking them to send you whatever you need is unlikely to yield positive results. Shifting to an approach where you treat them as partners rather than data sources changes the dynamic entirely.

Start with context. Explain the “why”: what is the data supposed to feed into, and what is the commercial driver behind it? Is it for an LCA study, an EPD, a CBAM calculation, or ESPR compliance? Suppliers respond to specific context rather than vague requests, especially when they may be sharing confidential information about their internal processes.

Show what is in it for them. Transparency and traceability across a company’s operations and supply chains are increasingly sought by different stakeholders, including other customers requesting this data due to growing regulatory pressure or internal sustainability improvements, as well as consumers, investors, and governmental bodies. Environmental performance data is therefore becoming a competitive differentiator for suppliers, and those who can monitor and share it efficiently are increasingly winning contracts over those who cannot. Setting up the systems to do this is, in fact, just as much in their interest as it is in yours.

Offer something in return. On top of the benefits that the supplier could achieve by setting up the systems to monitor this type of data, make sure you also have your own input in returning the favour. Share the results of your assessment with them, show them where their material sits in the overall footprint, and highlight any particular hotspots that are directly relevant to them. Ultimately, this opens up conversations about shared challenges and drives longer-term collaboration, creating opportunities for more resilient supply chains. Beyond conventional financial incentives, deeper collaboration can also help with standardising practices, reducing work duplication, and sharing innovative ideas that drive further improvements. Miah et al. (2017) found that this kind of mutual benefit was one of the leading motivations for suppliers to engage with data requests in the first place.

Be honest about the effort. The data collection process can be time and resource-consuming, and it is important to acknowledge that openly rather than glossing over it. Offer them help in finding the most manageable and efficient approach for their specific situation rather than expecting them to figure it out alone, and if you have verified tools or templates that can support the process, share them upfront for encouragement.

Treat suppliers as partners, not data sources, and the dynamic changes entirely.

Back to top

Make requests specific, simple, and worthwhile #

Once you have set the context and presented the potential benefit-share model that could get their attention and encourage collaboration, the practical data requests themselves need to be well designed to not lose the momentum you have built in the relationship.

Ask briefly and simply for total figures, not normalised ones. Request exactly the information needed, nothing more. If you simply need their electricity consumption per tonne of output for a specific product line, ask for the total electricity usage in kWh from their utility bills and the corresponding production volume of the product in question. Requests for ready-to-use normalised figures or LCA-specific outputs are unlikely to be answered and are likely to be ignored. Where possible, an exemplary completed questionnaire or pre-filled template can be provided to show exactly what a response should look like, and for any more complicated requests, tips or further instructions can be included directly in the spreadsheet wherever they might be useful. Particularly for smaller suppliers, who may not have the internal systems to pull the data together, offering a short call to walk through the request or help them extract the information from their utility bills and production records might cost you an hour and can save weeks of back and forth.

Be clear about timelines. Give the supplier a reasonable deadline and explain why it matters. If a verification audit is scheduled for a specific month, or if a CBAM reporting deadline is approaching, say so. Urgency with context is motivating, whereas urgency without context is irritating.

Urgency with context is motivating. Urgency without context is irritating.

Back to top

Build trust through transparency #

Trust means that the supplier believes you will use their data responsibly, that you will not use it against them commercially, and that the effort they invest in the process will be valued.

Be transparent about how the data will be used. If the data feeds into a published EPD, or will be seen by a third-party verifier, explain it and provide the details of the process. Suppliers are far more willing to share sensitive production data when they understand exactly where it goes and who sees it.

Maintain honest dialogue when challenges arise. If the data a supplier provides does not look right, or if there are gaps, raise it directly and collaboratively. “This figure looks lower than we would expect for this process, can we walk through how it was calculated?” is very different from “this data is wrong.” Highlighting any concerns or issues about their data in a constructive way can also strengthen the relationship. When you raise problems collaboratively rather than critically, the supplier begins to see you as a reliable partner who is invested in getting things right, which helps secure the relationship long-term.

Follow through on commitments. If you promised to share the results of the assessment, do it. If you said you would only request data once a year, acknowledge and honour that. Broken commitments erode trust quickly, and once a supplier loses confidence in the process, re-engagement becomes significantly harder than the first round ever was.

Broken commitments erode trust quickly, and re-engagement becomes far harder than the first round ever was.

Back to top

Think longer-term, not transactional #

The biggest mistake companies make with supplier data collection is treating it as a one-off project. You commission an LCA, collect the data, file the report, and move on. Two years later, you need updated figures for a new EPD or a CBAM declaration, and you end up starting the whole engagement process from scratch.

Building data requests into your regular procurement cycle instead, for example by requesting updated figures annually or whenever major sourcing or process changes occur, turns supplier engagement from a standalone sustainability project into a normal part of how you manage your supply chain. It also signals to the supplier that this is a permanent expectation, not a passing initiative, which in itself encourages them to invest in the capacity to respond properly.

The biggest mistake companies make with supplier data collection is treating it as a one-off project.

Back to top

From better data to better decisions #

This long-term approach to supplier engagement leads not only to a more accurate assessment, such as an LCA or EPD that will withstand third-party verification or a CBAM declaration that avoids punitive default values, but the benefits extend further than that, having a more holistic effect across the business.

Identifying real reduction opportunities. Generic data tells you what a typical process looks like, whereas primary data tells you what your actual supply chain looks like. That specificity allows you to identify genuine hotspots and target changes where they will make the most difference. Importantly, identifying a high-impact supplier does not necessarily mean the answer is to replace them. Sharing your findings with that supplier gives them the opportunity to reduce their impacts instead, which benefits not only your products but every other customer they serve across multiple supply chains.

Stronger commercial relationships. Suppliers who have invested time in sharing data and understanding your environmental goals become more than transactional vendors. They become partners with a shared interest in outcomes, which opens the door to joint problem-solving, shared investment in efficiency improvements, and collaborative innovation that neither party could achieve alone.

Supply chain resilience. The visibility that comes from deeper supplier engagement also helps you identify risks earlier, such as dependency on a single source for a high-impact material, exposure to regions with volatile energy grids, or reliance on processes that may face regulatory pressure in the coming years.

Generic data tells you what a typical process looks like. Primary data tells you what your supply chain looks like.

Back to top

The big picture: moving toward sustainable supply chain management #

Everything described in this article, from mapping your supply chain and prioritising key suppliers to building collaborative relationships and using data to inform decisions, is, in practice, the foundation of sustainable supply chain management.

Most businesses that commission an LCA or EPD start by thinking about a single product assessment. However, the process of engaging suppliers, understanding how your products are made, and using that knowledge to inform sourcing and design decisions naturally evolves into something broader. It becomes a way of managing your supply chain with environmental impact as a core consideration alongside cost, quality, and reliability.

This shift, from one-off assessment to ongoing supply chain management, is where the real value lies. It is how companies move from reactive compliance to proactive improvement, and how supplier data collection ultimately transforms from an administrative task into a strategic capability.

How Below280 can help

At Below280, supplier data collection is a core part of the LCA, EPD, and CBAM work we deliver for manufacturers. We know from experience that the quality of the final assessment depends on the quality of the supplier engagement behind it.

We can help you design and manage the supplier engagement process, from identifying which suppliers to prioritise through to structuring the data request, supporting suppliers who need guidance, and incorporating the data into a robust LCA model. Whether you are starting your first product assessment or looking to improve the data quality behind an existing one, get in touch and we can discuss how to approach it.

Supplier data collection transforms from an administrative task into a strategic capability.

Back to top

FAQs #

What if my supplier refuses to share data or cannot provide what I need?

This is common, especially with smaller or less mature suppliers, and it should not stop you from progressing. LCA standards such as ISO 14040 and ISO 14044 allow the use of secondary data where primary data is unavailable, so the practical approach is to start with what you can get and improve iteratively. For suppliers that are reluctant due to confidentiality concerns, non-disclosure agreements, anonymisation of data in published outputs, and clear communication about how the data will be used can help build the trust needed for them to participate in future rounds.

How do I handle supplier confidentiality concerns?

The best approach is to be transparent from the start about who will see the data and how it will be used. Offering to sign a non-disclosure agreement, anonymising data in any public outputs (such as EPDs), and limiting the data request to what is genuinely needed for the assessment all help. Where suppliers are still reluctant, an intermediary such as an LCA consultant can sometimes hold the data on their behalf, providing only aggregated outputs back to you.

How long does it typically take to collect supplier data for an LCA?

The first round of supplier data collection usually takes between two and five months, depending on the number of suppliers involved, the complexity of the supply chain, and the maturity of the supplier relationships. Subsequent rounds are typically significantly faster, often completed in a few weeks once suppliers understand what is needed and have systems in place to respond.

How often should I request updated supplier data?

Annually is a good starting point, aligned with your own reporting or assessment cycle. You should also request updates whenever there is a significant change in the supplier’s process, energy source, or material inputs. Building this into your regular procurement review makes it part of the normal business rhythm rather than a separate exercise.

How do I prioritise which suppliers to engage with first?

The most effective approach is to run a screening assessment using spend-based or industry-average data to identify which materials and suppliers contribute most to your product’s environmental footprint. Focus first on the top 5 to 10 suppliers by impact, which typically account for the majority of the footprint, and also consider suppliers in emission-intensive sectors such as metals, chemicals, or energy-intensive processing, even if they represent a smaller share of your total spend.

Does Below280 manage the supplier engagement process directly?

Yes. As part of our LCA, EPD, and CBAM projects, we work directly with your suppliers to collect the data we need. We handle the communication, provide guidance and templates, and ensure the data meets the quality requirements of the assessment, which takes the burden off your team while maintaining your supplier relationships.

Back to top

Struggling to get primary data from your suppliers?

We help manufacturers build supplier engagement processes that actually work, turning generic industry averages into verified primary data for LCA, EPD and CBAM reporting. Talk to our team.


Global commercial consultancy • Horizon Europe, UKRI & Innovate UK research partner. Specialists in openLCA, and UK openLCA partner for GreenDelta.

News

Below280 – Science for Real-World Sustainability Decisions

Science for real-world sustainability decisions

ACT NOW.
WIN MORE.

Sustainability isn’t optional anymore, but it doesn’t have to be complicated. We handle the science. You handle the growth.

What we do

Prove it. Track it. Win with it.

Three services. One team. Everything your business needs to measure impact, meet compliance and grow.

Environmental Product Declarations (EPDs)

ISO 14025 compliant. Independently verified sustainability credentials that give specifiers and buyers the data to choose your product with confidence.

Learn more about Environmental Product Declarations

Life Cycle Assessment (LCA)

Raw material to end of life. Understand your product’s true environmental footprint, the evidence behind every EPD and smarter product decisions.

Learn more about Life Cycle Assessment

Carbon Border Adjustment Mechanism (CBAM)

The EU Carbon Border Adjustment Mechanism has been fully in effect since 1 Jan 2026. We help exporters and importers calculate embedded emissions and stay ahead of compliance.

Learn more about Carbon Border Adjustment Mechanism
ISO 14025

Compliant EPDs verified by third-party bodies

1 Jan 2026

CBAM fully in effect – are you compliant?

3 services

One team. Everything you need to measure and grow.

Ready to measure your impact and stay ahead of compliance?

Talk to the Below280 team about LCA, EPDs, and CBAM support tailored to your business.

Insights

A Net Zero UK: Ambition vs Reality

In the summer of 2019, the United Kingdom committed to reach net zero by 2050, legally pledging to reduce emissions by 100% compared to 1990 levels. Almost seven years on, how much progress have we really made? The picture was already mixed, but this week it became harder to defend, as the UK confirmed that it is halving its contribution to the UN’s Green Climate Fund by a cut of more than £800 million, leaving it, alongside the US, as the only countries to have rescinded or cancelled a pledge to the world’s largest dedicated climate fund.

Net zero delivery largely depends on two things in parallel: the policy commitments a government makes, and the funding, infrastructure, and regulatory mechanisms that turn those commitments into reality. This article looks at both. It covers the pledges that have shaped UK climate policy since 2024 and the decisions, like the choice to cut climate funding mentioned above, that have determined whether those pledges can actually be delivered.

Domestic climate ambition has held remarkably steady across UK governments since 2019. Net zero by 2050 was legislated under a Conservative government, the 2030 phase-out of internal combustion engine cars was twice committed to and once delayed, and the current Labour government has restored or strengthened most headline pledges. But the financial and infrastructure mechanisms required to deliver that ambition have been moving in the opposite direction. Overseas aid has been cut from 0.7% to 0.5% to 0.3% of gross national income between 2020 and 2027-28. Major delivery vehicles like the Public Sector Decarbonisation Scheme have been defunded. Large-scale renewable infrastructure has been rejected. International climate finance commitments have been halved or withdrawn. This article examines that gap.

Direct Pledges – Environment

Full Fact is a UK-based independent fact-checking charity, whose Government Tracker tool monitors 92 key pledges drawn from the 2024 election manifesto and subsequent announcements, rating each as achieved, appears on track, in progress, appears off track, not kept, unclear or disputed, or wait and see. Several environmental policies have been rated, such as;

AreaPledgeFull Fact Verdict 
Electric vehicles‘Labour will support the transition to electric vehicles … restoring the phase-out date of 2030 for new cars with internal combustion engines’Wait and see
Water pollution‘This Government will cut water companies’ sewage pollution in half by the end of the decade’Wait and see
Environmental prosecution‘We will give regulators new powers to … bring criminal charges against persistent law breakers [water companies]’Achieved

Full Fact, (2026, April 28), Government Tracker, Retrieved from Full Fact: https://fullfact.org/government-tracker/

Although two years into their term, we are still waiting to see if Labour’s efforts to support the uptake of electric cars will result in a complete phase out of new combustion engine cars by 2030, the infrastructure to support this like electric charging points does seem to be becoming a more frequent sight on our roads. Similarly, whilst data for the year 2025-26 has not yet been released, the achievement of handing prosecution power to regulators to bring criminal charges to companies who hinder such investigations will hopefully aid in the reduction of water companies’ pollution into natural bodies of water by 2030.

None of these pledges have been classed as ‘appears off track’, ‘not kept’ or ‘unclear or disputed’ which shows a clear commitment to improving the environmental situation in the UK. The consistency is promising, but these commitments only hold weight if delivery follows.

Direct Pledges – Energy 

Energy policy, however, tells a more encouraging story. These policies seem to be progressing more rapidly than other governmental areas, for example;

AreaPledgeFull Fact Verdict 
Independence‘A new Energy Independence Act will establish the framework for Labour’s energy and climate policies’Wait and see
Oil and Gas‘We will not issue new licences to explore new [oil and gas] fields’Appears on track
Coal‘We will not grant new coal licences’Appears on track

Full Fact, (2026, April 28), Government Tracker, Retrieved from Full Fact: https://fullfact.org/government-tracker/

The creation of the new publicly owned company, Great British Energy has been achieved, providing an early and tangible signal of the government’s intent. The refusal to license new oil, gas, or coal exploration marks a meaningful break from previous energy policy. Both are rated as appearing on track, suggesting the government is actively resisting pressure to reopen fossil fuel development. This is a position that has the potential to become harder to maintain as energy prices fluctuate and supply security debates resurface.

The Energy Independence Act remains a wait-and-see, which is unsurprising given its role as an overarching legislative framework rather than a single deliverable. Its progress will likely determine how cohesively the remaining pledges are delivered.

As with the environmental commitments, none of these energy pledges have been rated as ‘off track’, ‘not kept’, or ‘unclear or disputed’ which is a consistency that, two years into the term, points to a government that is holding its stated course on clean energy transition. Whether this holds up when the government is faced with harder trade-offs remains unknown.

Ready to turn your net zero commitment into verified action?

We help UK organisations produce the LCAs, EPDs, and carbon data that supply chain and regulatory requirements demand.

Book a free 30 min call →

Grid Reform

Behind the headline energy pledges, the mechanics of actually connecting renewable energy to the grid have been difficult. Until 2025 the connection system operated on a first-come, first-served basis, and by early 2025 the connection queue had reached over 700 GW of generation and storage projects, roughly four times what the country actually needs. Speculative applications were holding firm connection dates that genuine projects could not access, and the previous model was no longer fit for the scale of the energy transition.

So, in June 2025, the Connections Reform led by NESO, the National Energy System Operator, went live. It replaced the queue-based model with a readiness-based system, assessing roughly 3,000 projects and identifying 283 GW to move forward, of which 132 GW are targeted for connection by 2030 in support of the government’s Clean Power target. Because of an oversupply of battery energy storage system (BESS) projects in the queue, only those with ‘protected’ status received firm connection offers. Around 153 GW of BESS projects were not prioritised, with no realistic pathway to grid connection before 2035. Solar Energy UK, the trade body for the sector, described the outcome as “painful but necessary”.

The process also ran into serious execution problems. NESO missed multiple self-imposed deadlines for issuing connection offers, with the operator itself acknowledging “considerable uncertainty” throughout, and conceding that delays were creating uncertainty around resourcing and investment. Gate 2 Phase 1 transmission offers for projects connecting before 2030 are now not expected until mid-2026 at the earliest. This means that developers who had invested years and significant capital into projects expecting a 2028 or 2029 connection have been hit hard. The reforms are a necessary response to the broken system, but the execution has added a further layer of uncertainty to an already strained supply chain.

Also in June 2025, the UK government rejected the Xlinks Morocco-UK Power Project. The project had been designated a Nationally Significant Infrastructure Project by the previous government in 2023 and had progressed through development for over six years.

The project proposed building 11.5 GW of solar and wind generation in Morocco’s Guelmim-Oued Noun region, paired with 22.5 GWh of battery storage, and transmitting the power to Britain via a 4,000 km HVDC subsea cable. The numbers were striking: 8% of UK electricity supply, a projected 10% reduction in power sector CO₂ emissions in its first year, a 9.3% reduction in wholesale electricity prices, £20 billion in socio-economic value, and £5 billion directly into UK green industries.

At the time, Xlinks had secured backing from TotalEnergies, Abu Dhabi National Energy Company, and Octopus Energy, with £5 billion of equity finance lined up and no government investment required. The company was seeking a Contract for Difference, a standard government mechanism guaranteeing a price for the electricity generated, at approximately half the cost of new nuclear energy but the government declined.

The consequences extended beyond the project itself. XLCC, a Scottish company that had planned to manufacture the four giant cables at a new factory at the Port of Hunterston in North Ayrshire, saw its business collapse alongside the decision. Xlinks has since established a German subsidiary, Xlinks Germany GmbH, which is developing a separate Morocco-to-Germany project called Sila Atlantik, backed by E.ON and Uniper and now formally supported by the German federal government.

Public Sector Policies

Beyond direct government pledges, institutional commitments across the public sector are reshaping how organisations operate and what they demand from their suppliers. Several institutions have imposed mandatory net zero targets or are requiring a demonstrable commitment to sustainability:

  • NHS England – commits to net zero direct carbon emissions by 2040, and net zero indirect emissions like those from the supply chain or patient and staff travel by 2045.
  • Local Authorities – many pledge to reach net zero before the national target with a significant number committing to dates as early as 2030, by delivering on the ground impactful projects to mitigate climate change.
  • Educational Institutions – fall into the same national net zero by 2050 target, with new school buildings designed to a zero carbon standard since 2022.

Over the past five years, the NHS and local authorities in England have made measurable progress on estate decarbonisation, tightened supplier requirements through Carbon Reduction Plans and Environmental Product Declarations, and implemented local green plans. A significant proportion of the capital behind this progress, particularly for heat pump installation, fabric upgrades, and solar deployment across hospitals, schools, and council buildings, came through the Public Sector Decarbonisation Scheme administered by Salix Finance.

From 2025, educational settings in the UK are required to have a Sustainability Lead and a Climate Action Plan, CAP, in place. These CAPs ensure that each individual school can progress towards sustainability targets in a bespoke and manageable way. This means that improvements so far have largely been focused on reducing operational carbon of current school buildings, and there are efforts to only continue this progress and work towards reducing embodied carbon emissions in new build schools.

Cancellation of the Public Sector Decarbonisation Scheme

Much of the aforementioned decarbonisation momentum was funded, in part, by the Public Sector Decarbonisation Scheme (PSDS). This is a programme administered by Salix Finance on behalf of the government since 2020, and has awarded over £3.5 billion in grants across nearly 1,400 projects for measures including heat pumps, solar panels, insulation, and glazing upgrades in schools, hospitals, and council buildings.

Following the 2025 Spending Review, the government confirmed it would commit no further investment to the PSDS beyond already-awarded projects. Existing phases (Phase 3c and Phase 4) are due to continue to completion in March 2026 and March 2028 respectively, but there will be no Phase 5 and likewise, no replacement has been announced.

The practical consequences of this are significant. Many local authorities had set 2030 net zero targets for their estates which may become increasingly hard to reach without continued PSDS investment. Similarly, decarbonising complex buildings such as schools, swimming pools, and hospitals takes years of planning, procurement, and delivery. This abrupt end to the funding pipeline disrupts the planning horizon at precisely the point when the market has scaled up to meet it. Contractors, heat pump installers, and sustainability consultancies that built capacity around PSDS delivery now face the loss of their core customer base. The Low Carbon Skills Fund, which helped public sector organisations develop heat decarbonisation plans in the first place, was also cancelled for 2025/26, removing even the advisory layer of the programme. The result is a public sector net zero programme that has, in effect, been defunded mid-journey, with many small scale consultancies and contractors caught in the crossfire.

International Standing

On the global table, the UK’s policy decisions have weakened its position internationally. At COP30 in Belém in November 2025, Brazil launched the Tropical Forests Forever Facility (TFFF), a results-based finance mechanism designed to make standing forests more valuable than cleared ones. The initiative originated in the UK and was shaped in part by the British government and British financial institutions. But when Keir Starmer arrived in Belém, he came with no pledge to invest. Norway committed $3 billion, Germany €1 billion, France €500 million, Brazil and Indonesia $1 billion each. The UK, which hosted COP26 in Glasgow and championed international forest protection, contributed nothing, citing domestic fiscal pressure as the reason. The situation was worsened diplomatically by Prince William having been in Rio de Janeiro the day before, naming the TFFF an Earthshot Prize finalist. At the time, our director, Tom Bradley, was at industry events for COP30 in São Paulo, and the mixed messaging and effective insult to Brazil during COP30 were mentioned by other delegates. The instrument the UK had helped design proceeded without British funding.

That pattern has continued into 2026. This week, the UK notified the Green Climate Fund, GCF, that it is cutting its pledge for the fund’s second replenishment cycle by approximately 50%, reducing it to only £815 million. The move follows Donald Trump’s administration rescinding the US’s $4 billion pledge a year prior, and the UK and US are now the only countries to have cancelled a commitment to the fund. The GCF’s chief executive confirmed the cut is expected to have a material impact on project delivery. The government cited its decision to reduce overseas aid from 0.5% to 0.3% of gross national income and prioritise domestic security spending. Other major economies including Germany and France have also trimmed climate finance budgets, but neither has rescinded a GCF pledge.

The Expert Verdict 

The Climate Change Committee, the independent body which reports to Parliament on emissions reduction progress, advised in 2019 that Scotland could reach net zero by 2045 and Wales could achieve a 95% reduction by 2050. Both nations went on to legislate this. Scotland’s 2045 target is now law under the Climate Change (Emissions Reduction Targets) (Scotland) Act 2019, and Wales went further than the original Committee advice, legislating full net zero by 2050 in 2021. However, in April 2024 the Scottish Government scrapped its 2030 interim emissions reduction target after admitting it was no longer achievable.

The Committee also states that “it is achievable with known technologies, alongside improvements in people’s lives, and within the expected economic cost that Parliament accepted”. This indicates that the solutions exist and the costs are understood, but the Committee is equally direct about what is missing, warning that this outcome “is only possible if clear, stable and well-designed policies to reduce emissions further are introduced across the economy without delay” and that “current policy is insufficient for even the existing targets.”

Climate Action Tracker reinforces this, rating the UK’s overall policies and action as ‘insufficient’. The gap between what is technically possible and what policy currently supports is not a minor shortfall. Cancelling the PSDS, rejecting Xlinks, and attending COP30 without financial commitments are examples of the kind of policy choices that are inconsistent with the legislated trajectory.

Are We on Track?

The overall picture is one of genuine but uneven progress. This article covers only part of the landscape, but the decisions discussed are representative of where the UK stands.

Real progress has been made towards a net zero UK by 2050. Great British Energy has been established, new fossil fuel licences have been refused, supply chain requirements have been tightened through Carbon Reduction Plans and Environmental Product Declarations, and schools are now legally required to have Climate Action Plans in place. The decisions described in this article sit alongside those achievements. The PSDS has been defunded, removing the primary capital mechanism for public sector decarbonisation. The Xlinks rejection ended a proposal for privately financed generation that would have supplied 8% of UK electricity. The grid reform was structurally necessary, but its execution caused investment delays and removed significant volumes of consented capacity from the connection pipeline. At COP30, the UK helped design the Tropical Forests Forever Facility but did not commit financial backing at launch. And this week, the UK halved its contribution to the UN’s Green Climate Fund, the primary financial vehicle for the Paris Agreement’s implementation in 134 developing countries.

These decisions are not isolated. The retreat from delivery mechanisms has been running since around 2020 and has continued across two governments. The UK has maintained net zero ambition in legislation while withdrawing the means of delivery for six years across both parties, and 2025-2026 is the most acute phase of that pattern. Domestic ambition has held in law. The funding, infrastructure, and international finance required to deliver that ambition have not.

Progress remains uneven, and the Climate Change Committee is clear that current policy is insufficient to meet existing targets. Closing the gap between ambition and delivery will be the central challenge of the next 24 years.

At Below280, we help organisations move from commitment to measurable action. Whether that means conducting a Life Cycle Assessment (LCA) to understand where emissions occur across a product full lifespan, producing an Environmental Product Declaration (EPD) to meet supply chain requirements like those now demanded by the NHS and local authorities, carrying out a Whole Life Carbon Assessment (WLCA) to quantify embodied and operational carbon in the built environment, or navigating the UK’s incoming Carbon Border Adjustment Mechanism (CBAM). 

Frequently Asked Questions

Progress has been made but the Climate Change Committee warns that current policy is insufficient to meet existing targets. Significant steps like the creation of Great British Energy and the refusal of new fossil fuel licences are positive, but delivery across all sectors needs to accelerate.

Great British Energy is a new publicly owned energy company established by the Labour government as part of its clean energy transition. It represents one of the more tangible early signals of the government’s commitment to moving away from fossil fuels.

Carbon Reduction Plans (CRPs) are required for UK businesses bidding on public contracts over £5 million under PPN 06/21. They set out a company’s current carbon footprint and commitment to reaching net zero by 2050.

An EPD is a verified document that communicates the environmental impact of a product across its lifecycle, based on a Life Cycle Assessment. They are increasingly required by public sector procurement, BREEAM, and supply chain requirements like those from the NHS.

The Committee states that net zero is achievable with known technologies and within expected economic costs, but warns that current policy is insufficient and that clear, stable policies must be introduced across the economy without delay.

Ready to turn your net zero commitment into verified action?

We help UK organisations produce the LCAs, EPDs, and carbon data that supply chain and regulatory requirements demand. Talk to our team.


Global commercial consultancy • Horizon Europe, UKRI & Innovate UK research partner. Specialists in openLCA, and UK openLCA partner for GreenDelta.

Sources 

House of Commons Library – Net Zero

Institute for Government – Net Zero

Full Fact – Government Tracker

NHS England – A Net Zero NHS

Local Government Association – Local Net Zero

Forbes Solicitors – Net Zero Education Review

European Commission – CBAM

UK Government – CBAM Policy Summary

Climate Change Committee – Net Zero

Climate Action Tracker – UK

Written by Helen Brown

Insights

How to Calculate Embedded Emissions for UK Aluminium Manufacturers

If you make aluminium products and export to the EU, your customers are already asking for embedded emissions data. From January 2026, EU CBAM (Carbon Border Adjustment Mechanism) entered its definitive phase, which means the carbon content of your products is now a direct cost for whoever imports them. Get the number wrong or leave it blank, and they pay more. Get it right, and you protect the relationship.

This guide explains exactly what embedded emissions are, how to calculate them, and what UK aluminium manufacturers need to do to stay on the right side of their EU customers.

Embedded emissions are the greenhouse gases released during the production of a good, up to the point it leaves your factory gate. For aluminium, this covers:

Direct emissions (Scope 1): the carbon released from your own production processes, such as combustion in furnaces, use of fossil fuels for heating, process emissions from smelting or casting, and the use of chemical reagents in production.

Indirect emissions (Scope 2): the emissions from the electricity you consume in manufacturing. For aluminium, this is significant because electrolytic smelting is energy-intensive, and the carbon intensity of that electricity depends on when and where it was generated. Note that electrolytic smelting is only relevant if you are producing primary aluminium from base ore. Most downstream aluminium manufacturers working with ingot or billet will not have this process in scope.

Precursor emissions: if your aluminium product uses aluminium ingot, billet, or other semi-finished materials as inputs, the embedded emissions from those upstream materials must also be included. These are often the largest share of the total.

The boundary for CBAM is modules A1 to A3 under EN 15804, which maps to cradle-to-gate. You are not required to include transport to the customer or end-of-life, but you do need everything up to the factory gate.

This is where many manufacturers get tripped up. A Life Cycle Assessment (LCA) gives you a comprehensive picture of your product’s environmental impact across multiple categories. An Environmental Product Declaration (EPD) communicates that data in a standardised format.

But CBAM does not simply accept an LCA or EPD as proof of embedded emissions. The EU’s Monitoring and Reporting Regulation (MRR) requires installation-specific, meter-based data. That means:

  • Emissions must be traced to your specific production installation, not an industry average
  • Electricity must be attributed using a time-weighted carbon intensity factor for the grid you actually use
  • Any precursor materials must have their own verified emissions data, not generic database values

If you cannot provide verified actual emissions, your EU customer must use region-specific default values. These are calculated as the average of the 10% worst-emitting production sites in that region, not a single EU-wide figure. For most UK manufacturers, those default values will be higher than your actual emissions, which means your customer overpays on certificates and you look like a high-carbon supplier.

Identify which products are in scope and trace each one back to its production installation. For a UK aluminium extruder, this means the extrusion facility itself, but also the source of the aluminium billet you use as feedstock.

Gather actual metered data from your installation for the reporting period, typically a calendar year. This includes fuel consumption by type, electricity consumption, and production volumes. The data needs to be traceable, ideally from your energy invoices and production records.

Apply the EU-approved emission factors for each fuel type to your fuel consumption data. These are set by the EU MRR and are not the same as DEFRA emission factors, so you need to use the right source.

Multiply your electricity consumption by the carbon intensity of your national grid, using the country-specific electricity emission factor published by the EU for the relevant year. For UK installations, there is a specific factor available.

If you use primary aluminium as an input, you need verified embedded emissions data for that aluminium from the smelter or supplier. This is where the process gets complicated. If your supplier cannot provide verified data, region-specific default values apply for that portion.

Divide total direct and indirect emissions by the quantity of product produced in tonnes. This gives you the embedded emissions intensity figure your EU customer needs.

Embedded emissions intensity formula

Direct emissions
Scope 1 (tCO2e)
+
Indirect emissions
Scope 2 (tCO2e)
+
Precursor emissions
Upstream inputs (tCO2e)
÷
Production volume
Tonnes produced
=
tCO2e/t
Embedded emissions intensity

This is the figure your EU importer needs for their CBAM declaration.

This is the document you provide to your EU importer. It must follow the format specified by the European Commission and include your installation details, the calculation methodology, the emissions intensity figure, and any carbon price already paid in the UK.

Even though an EPD alone does not satisfy CBAM, it significantly reduces the work involved. A well-constructed EPD for an aluminium product contains most of the primary data and calculation logic CBAM requires. The system boundary overlaps almost entirely, and the verification process for an EPD gives you an audit trail that CBAM verifiers will recognise.

If you already have an EPD or are planning to get one, the marginal effort to produce CBAM-ready embedded emissions data is much lower. The datasets, the allocation methodology, and the verification evidence are largely the same.

This matters because CBAM verification is mandatory from 2026. Your embedded emissions data must be independently verified by an accredited third party, including an on-site audit in the first year. Starting with a rigorous LCA and EPD foundation makes that verification faster and less painful.

EU CBAM applies to goods imported into the EU now. UK CBAM is expected to follow a similar structure and is currently scheduled to take effect from January 2027, covering aluminium, cement, fertiliser, hydrogen, and iron and steel.

If you manufacture aluminium products sold in the UK market, the same embedded emissions calculation methodology will apply domestically within the next 12 months. Building the data infrastructure now means you will be ready for both regimes without duplicating the work.

No. An LCA provides valuable primary data, but CBAM requires installation-specific metered data calculated using the EU MRR methodology. An LCA is a strong starting point, not a direct substitute.

If you cannot obtain verified data from your supplier, region-specific default values apply for that precursor. These are based on the average of the 10% worst-emitting production sites in the relevant region. This will likely overstate your actual embedded emissions and increase your customer’s CBAM certificate cost.

From 2026, yes. Supplier-specific emissions data used in CBAM declarations must be verified by an accredited third-party verifier. The first verification includes an on-site audit.

It is the document UK exporters provide to their EU importers summarising embedded emissions per tonne of product, the calculation methodology, and any carbon price already paid. It follows the format set by the European Commission.

UK CBAM is expected to follow a similar structure, with full implementation from January 2027. It will cover the same broad product categories. UK manufacturers exporting to the EU face EU CBAM obligations now; those selling domestically will face UK CBAM obligations from 2027.

Yes. Below280 provides embedded emissions calculations for CBAM compliance, including primary data collection, EU MRR-aligned methodology, and support through the verification process. We also produce EPDs that create a reusable data foundation for ongoing CBAM reporting.

Working through your first CBAM submission?

If your EU customer has started asking for a Communication Summary Sheet, we can help. We calculate your embedded emissions, prepare the documentation, and support you through verification.


Global commercial consultancy • Horizon Europe, UKRI & Innovate UK research partner. Specialists in openLCA, and UK openLCA partner for GreenDelta.

News

Below280 Launches to Help Manufacturers Navigate the New Era of Environmental Compliance

A specialist consultancy focused on LCA, EPD, and CBAM is entering the market at exactly the right moment

[Cramlington, 18th March, 2026] Below280 has officially launched as a dedicated sustainability consultancy built to help manufacturers understand, measure, and communicate the environmental impact of their products.

What Does “Below280” Mean?

The name says it all. 280 parts per million is the pre-industrial CO₂ baseline, the world before significant human induced climate change. Below280 exists to help businesses take the steps that actually move the needle back.

LCA, EPD and CBAM Under One Roof

With growing pressure from the EU and UK Carbon Border Adjustment Mechanism (CBAM) and rising demand for verified Environmental Product Declarations (EPDs) and Life Cycle Assessments (LCA), manufacturers are facing a compliance landscape more complex than ever.

“The regulations and requirements are coming whether businesses are ready or not. Below280 exists to make sure they are. We have a strong history of delivering LCA, starting out as part of Narec, and then Decerna, and now as an independent company. If you want high quality LCA studies that can help you not only fit with regulations, but make active changes to your product, this is what we do,” said Tom Bradley, Director at Below280.

As modern methods of construction and sustainable building claims come under scrutiny, LCA is fast becoming the proof that backs them up.

Unlike generalist sustainability consultancies, Below280 brings deep technical expertise to a focused set of services; meaning clients get specialists, not generalists, working on the issues that matter most to their business right now. Below280 is open for business and working with manufacturers across the globe.

Below280 has a strong history of LCA, existing as part of the sustainability consultancy Decerna since 2012, and prior to that, being the LCA services of Narec since 2010.

For enquiries, visit www.below280.com or contact info@below280.com

About Below280 Below280 is a UK-based sustainability consultancy specialising in Life Cycle Assessment, Environmental Product Declarations, and CBAM compliance.

Insights

Part Z and Embodied Carbon Guide

The UK Government faces an imminent decision on embodied carbon regulation. And the clock is ticking on Net Zero targets. Embodied carbon now threatens to overtake operational energy use. It is becoming the sector’s primary carbon source, leaving the UK’s construction industry no longer wondering whether embodied carbon regulation is necessary, but how long the UK can afford to delay its assessment. This article discusses the differences between operational and embodied carbon, explores the barriers, benefits and support of mandatory reporting and why this matters within the UK construction industry.  


Embodied carbon is defined as the total carbon emissions produced throughout a building’s entire lifecycle, excluding its operational energy use. It contributes to roughly 20% of UK built environment emissions currently, but this is ever rising. Due to buildings increasing in energy-efficiency and grid decarbonisation, operational carbon is falling, meaning that embodied carbon will account for over half of built environment sector’s emissions by 2035. 

Operational Carbon vs Embodied Carbon 

As embodied carbon is released upfront, it cannot be reduced post-build unlike operational carbon which you can improve over time through retrofits or switching renewable energy. Consequently, regulatory targets, and standardisation methods of measurement are likely to help quantify emissions, develop science-based targets and hold building developers accountable. However, embodied carbon remains largely unregulated in the UK, resulting in a fall of only 4% between 2018 and 2022, 13% off the reduction target. Compared to operational carbon, these fell successfully in line with stated targets supported by extensive regulation. 

 Operational Carbon Embodied Carbon 
Definition Carbon emissions arising from the energy used to operate a building during its lifetime Carbon emissions from the materials and construction processes used throughout a building’s lifecycle 
Practical Example Electricity powering office lighting and IT equipment  Air conditioning cooling a commercial building Concrete and steel manufacturing and transport   Demolition waste processing 
Mitigation Strategies Improved insulation and airtightness  Renewable energy generation   Energy-efficient appliances Using less material and low carbon or recycled alternatives  Local material sourcing  Building reuse and retrofit  
Supporting UK Regulation Extensively documented:  Building Regulations Part L (Conservation of Fuel and Power)   Future Homes Standard 2025   Energy Performance Certificate (EPC) requirements Currently unregulated, industry-led initiatives include:   Part Z Building Regulations   RICS Whole Life Carbon Assessment and the   Net Zero Carbon Buildings Standard 

Part Z – Industry-led Change  

Part Z is an industry-proposed amendment to the UK Building Regulations 2010, written to require developers to assess and limit the whole-life carbon emissions of new construction projects. Under Part Z, large projects — over 1,000m² or 10 homes — must first report their carbon emissions. Stricter limits on upfront embodied carbon come next. The goal is to regulate the carbon footprint of the construction industry.

Barriers to Regulation 

This approach is backed by industry leaders such as the Institution of Structural Engineers (IStructE) and UK Green Building Council (UKGBC) and supported by a further 105 company pledges. However, almost 5 years on from its original proposal, it is still yet to become law. This has led to pressing questions arising about the UK Government’s priorities regarding the UK construction industry, and its responsibility within net zero targets. 

In an interview with Will Arnold, of IStructE and an author of Part Z, The Building Cost Information Service suggests that government hesitation comes from concerns about meeting housebuilding targets. This uncertainty stems from the effects that implementing this policy could have on increasing the difficulty of building much needed homes. However, Arnold, explains that the regulation could still be applied to larger developments, to avoid building unnecessary barriers for smaller projects. Increasing project costs by undertaking an embodied carbon assessment is also a key worry, but this fails to recognise the monetary positives in increasing material efficiency, reuse and transport distances, all arising from reducing embodied carbon.  

Looking further afield, the European Union has taken a progressive approach, mandating Member States to report embodied carbon by 2028. The Energy Performance of Buildings Directive (EPBD) requires that all new buildings must calculate and report whole-life carbon emissions, plus member states must establish maximum thresholds for embodied carbon, which will gradually decrease after 2030. Prior to the implementation of the EPBD, several EU countries already had national regulation regarding embodied carbon, showing a clear recognition and commitment to eliminating this major contributor of emissions. 

The Benefits of Lowering Embodied Carbon 

Despite Part Z not becoming regulation, industry continues reducing embodied carbon, and the UK Green Building Council published the Net Zero Carbon Buildings Standard in 2024. This document calls for the assessment of both embodied and operational carbon using a whole life carbon approach. Similarly, developers can elect to assess their embodied carbon emissions on a project-by-project basis. This approach demonstrates environmental leadership for those who choose it, whilst meeting the rising demand from both industry stakeholders and the public. 

  • The Forge, London, United Kingdom, 2023 

The Forge, a collaboration between Landsec, Bryden Wood and Easi Space is a development of two nine-storey commercial office buildings in London. It is the world’s first major commercial building constructed using a platforms approach to Design for Manufacture and Assembly (P-DfMA). It also used a minimised basement size, decarbonised MEP services (using heat pumps instead of gas) and opted for low carbon material specifications resulting in a 39% reduction in upfront embodied carbon. Further calculations tracked changes from the baseline through to completion in 2023 and found that embodied carbon accounts for roughly two-thirds of whole life carbon over 60 years, with operational carbon making up the remaining third. 

Timeline to Implementation 

Embodied carbon is soon to dominate built environment emissions, yet it remains largely unregulated in the UK. Thoughtful design and material choices reduce emissions, but progress depends on voluntary action and industry leadership without regulatory backing. As operational carbon continues to fall and embodied carbon’s share grows, the case for regulation becomes harder to ignore. Seemingly, one question remains; how long will the UK wait to implement embodied carbon regulation? 

Supporting Your Embodied Carbon Reporting 

Decerna helps UK construction organisations navigate new compliance requirements through our comprehensive consultancy and development services. Our extensive experience in Life Cycle Assessment makes us one of the longest-established UK consultancies in this field, offering ISO 14040/44 LCAs and EPDs, along with WLCA and Embodied Carbon Assessments. Our capabilities extend to providing Carbon Border Adjustment Mechanism support, comprehensive carbon reporting covering all Scope 1, 2 and 3 emissions, and developing bespoke carbon reduction and Net-Zero plans. 

Written by Helen Brown 

Does your product need an embodied carbon declaration?

Part Z is coming. Below280 produces ISO 14040/44 compliant LCAs and EN 15804 verified EPDs for UK construction product manufacturers — the documentation specifiers and procurement teams are already asking for.


Global commercial consultancy • Horizon Europe, UKRI & Innovate UK research partner. Specialists in openLCA, and UK openLCA partner for GreenDelta.
News

EU Publishes Long-Awaited Amending Regulation to Simplify CBAM

The European Union has published Regulation (EU) 2025/2083, amending the Carbon Border Adjustment Mechanism (CBAM) Regulation (EU) 2023/956. These amendments follow extensive data collection and stakeholder feedback during the transitional period.

Adopted on 8 October 2025 and published on 20 October 2025, the regulation introduces substantial simplifications, aimed at reducing administrative burden without compromising environmental integrity.

Key changes include:

  • A new exemption threshold, establishing a 50-tonne threshold per importer annually for certain goods.
  • Declaration deadlines extended from 31 May to 30 September
  • Simplified default emission values based on highest-emitting exporting countries
  • System boundaries aligned with EU Emissions Trading Scheme for certain aluminium and steel products
  • Commission-published default carbon prices for third countries with carbon pricing systems
  • Clarified obligations for indirect customs representatives

The amending regulation demonstrates the EU’s responsiveness to implementation challenges, whilst preserving the CBAM’s environmental objectives.

CBAM is changing. Is your compliance data keeping up?

Regulation changes do not pause your obligations. UK manufacturers exporting steel, aluminium, cement, fertilisers or hydrogen to the EU still need verified embedded carbon data — and your EU importers need it now. Below280 keeps your CBAM documentation current as the rules evolve.


Global commercial consultancy • Horizon Europe, UKRI & Innovate UK research partner. Specialists in openLCA, and UK openLCA partner for GreenDelta.
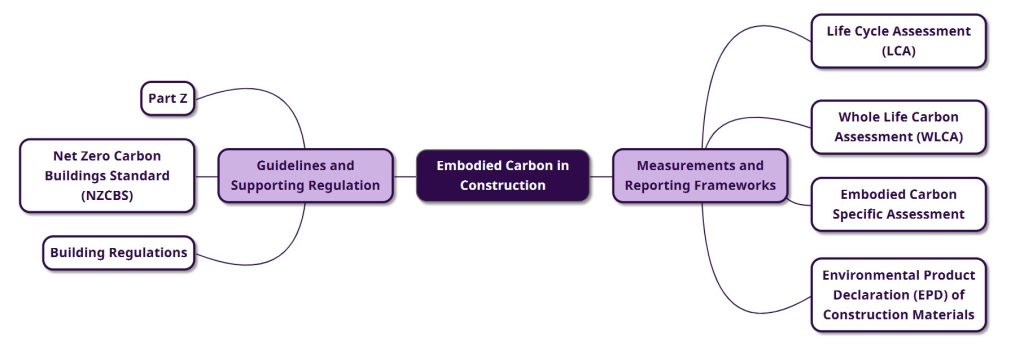
News

Tees Valley Net Zero and Environmental Product Declarations (EPD) Programmes 

Supporting 670 businesses across the Tees Valley 

Overview 

The Tees Valley is home of many businesses, many of which are central to the UK’s industrial base and net zero ambitions. Funded through the UK Shared Prosperity Fund (UKSPF), the Tees Valley Net Zero (TVNZ) and Environmental Product Declarations (EPD) programmes were designed to help local SMEs decarbonise, improve energy efficiency, and prepare for emerging regulations like the EU Carbon Border Adjustment Mechanism (CBAM) and mandatory carbon reporting. 

Through tailored support—from carbon reduction planning and Life Cycle Assessments (LCAs) to EPD certification and CBAM readiness—the programme supported 670 businesses across the region. 

Key Findings:  

Category Key Result 
Businesses Supported 670 businesses across the Tees Valley 
Economic Impact 500 businesses provided with grants 
Carbon Savings 250 tonnes CO₂e

Innovation Benefits 

  • 82% of businesses said the benefits wouldn’t have happened in the same way without the support 
  • 97% of firms have, or will, improve energy efficiency 
  • 92% of firms have, or will, reduce their energy costs 
  • 80% of respondents have, will, or may develop a decarbonisation plan or EPD certification 

Commercial Benefits 

The programme also helped businesses overcome key barriers to commercial success: 

  • 49% → 10% reduction in businesses facing lack of market knowledge 
  • 27% → 10% reduction in technological constraints 
  • 29% → 4% reduction in risk of failure 
  • 27% → 6% reduction in firms lacking collaborators 

Quality of Service 

Client feedback showed extremely high satisfaction levels: 

  • 100% of respondents were satisfied with the programme 
  • 100% rated the team’s knowledge/expertise as “Excellent” or “Good” 
  • 97% rated the relevance/quality of advice as “Excellent” or “Good” 
  • 97% rated Net Zero advisor consultations as “Excellent” or “Good” 

Conclusion 

The TVNZ and EPD programmes clearly demonstrated the value of targeted, expert-led sustainability support. By helping businesses reduce emissions, navigate new regulations such as CBAM, and prepare for low-carbon growth, the programme contributed significantly to the Tees Valley’s economic and environmental future. 

Does your combined authority need EPD support for local businesses?

Below280 partners with combined authorities and local enterprise partnerships to deliver EPD and LCA programmes for manufacturers in their region. If you represent a council, LEP, or growth hub looking to support businesses with sustainability compliance, get in touch.


Global commercial consultancy • Horizon Europe, UKRI & Innovate UK research partner. Specialists in openLCA, and UK openLCA partner for GreenDelta.

Insights

UK Sustainability Regulations 2025: What Your Business Needs to Know 

The UK’s regulatory landscape is rapidly transforming sustainability into a fundamental business imperative. Recent updates to environmental legislation and related frameworks create a more demanding compliance environment. Organisations must utilise 2025 as a critical preparation period to address increasingly stringent ESG requirements, enhance supply chain transparency, and develop robust strategies to meet ambitious carbon reduction targets. 

Legislative Updates 

Carbon Border Adjustment Mechanism – CBAM  

For importers and exporters, the EU Carbon Border Adjustment Mechanism (CBAM), a scheme which puts a carbon price on imports of carbon-intensive goods to prevent carbon leakage has undergone significant simplification in early 2025. A new de minimis threshold now exempts importers handling less than 50 tonnes annually. This covers iron, steel, aluminium, cement, and fertiliser sectors. This change affects approximately 90% of importers whilst still capturing over 99% of embedded emissions. Notably, electricity and hydrogen sectors remain exempt from this threshold, with algorithm-based calculations and anti-abuse provisions added, ensuring compliance through customs declarations and monitoring. 

For larger importers, several streamlining measures have been implemented, including a simplified authorisation procedure, reduced verification requirements for emissions calculations, decreased financial liability with certificate holding requirements dropping from 80% to 50%, and extended reporting deadlines from May to August. The implementation timeline has been adjusted, with certificate sales for 2026 emissions beginning in February 2027, further reflecting EU ETS. 

Corporate Sustainability Reporting Directive – CSRD 

The Corporate Sustainability Reporting Directive (CSRD) requires qualifying companies to publish detailed sustainability information in their management reports covering environmental, social and governance impacts. Companies must follow the European Sustainability Reporting Standards (ESRS). This includes a double materiality perspective — reporting both how sustainability issues affect the business and how the business affects people and the environment.

As of February 2025, the scope of the CSRD has been reduced to only companies with over 1,000 employees (and either €50M turnover or €25M balance sheet), exempting approximately 80% of previously in-scope companies. It introduces a two-year postponement for implementation timelines, establishes value chain protections limiting information requests from smaller firms, simplifies the ESRS standards, eliminates sector-specific standards requirements, modifies assurance requirements by removing potential upgrades to reasonable assurance, and creates voluntary reporting options for companies not in scope. These changes aim to reduce administrative costs by an estimated €4.4 billion annually whilst maintaining the core sustainability disclosure principles of the directive. 

Corporate Sustainability Due Diligence Directive – CSDDD 

The Corporate Sustainability Due Diligence Directive is an EU legislation requiring large companies to identify, prevent, mitigate and account for adverse human rights and environmental impacts in their own operations, subsidiaries and value chains. It also obliges companies to adopt transition plans for climate change mitigation on a best effort basis.  

The February 2025 simplification package introduces several key changes, including postponed implementation timelines (delayed to July 2027 and first application to July 2028), streamlined value chain assessment requirements that limit due diligence, and simplified process requirements such as reducing assessment frequency from annual to every five years. The update also removes the EU-wide civil liability regime in favour of national systems and better aligns climate plan requirements with existing Corporate Sustainability Reporting Directive (CSRD) standards. These adjustments aim to reduce compliance costs whilst maintaining core environmental and human rights protections. 

The Built Environment  

National Planning Policy Framework – NPPF  

The December 2024 updated National Planning Policy Framework (NPPF) contains significant amendments concerning climate change, which make explicit that climate adaptation and mitigation are now central to decision-making.  The major update is quoted as “the need to mitigate and adapt to climate change should also be considered in preparing and assessing planning applications, taking into account the full range of potential climate change impacts.”  

Those bringing forward planning applications must now provide information concerning the climate impacts of the proposed development and measures taken to adapt to the new requirements. Evidence of such considerations may include; whole-life carbon assessments and quantification of the projects embodied carbon emissions, which provide information about both operational carbon emissions, along with upstream and downstream Scope 3 emissions of the project. The framework also gives significant weight to renewable and low carbon energy generation. 

Building Regulations 

The Department for Levelling Up, Housing and Communities (DLUHC) has announced significant updates to England’s Building Regulations, effective 15 June 2025. These changes represent an important step towards the Future Homes Standard in 2025 and support the UK’s target of achieving net-zero carbon emissions by 2050. 

More stringent energy efficiency requirements have been introduced, with new build homes required to cut carbon emissions by approximately 30% and new commercial buildings by 27% compared to current standards. Within this, Approved Document O addresses the issue of overheating in new residential buildings and establishes a new ‘Primary Energy’ metric, alongside CO2 measurements, to assess energy efficiency compliance. This now takes into account factors such as heating system efficiency and energy production impacts. These measures aim to increase the proportion of homes rated C or above for energy efficiency, which currently stands at 46% compared to just 14% in 2010. New requirements for offices are also included, detailing standards for the use of recirculating ventilation systems and mandatory CO2 monitors. 

Construction Products Regulation – CPR 

The revised Construction Products Regulation (CPR) of January 2025, modernised the previous 2011 rules to address shortcomings in the single market for construction products. The update tackles inconsistent implementation across Member States, simplifies the complex legal framework, and better supports green and digital transitions whilst ensuring product safety. 

Key updates include the introduction of Digital Product Passports (DPPs) that serve as centralised digital records containing technical specifications and environmental data, improving product traceability throughout the EU market. The CE marking has been expanded beyond technical performance to incorporate environmental impact assessments, and manufacturers must now report on climate-related factors such as CO2 emissions and energy consumption for key construction products. These changes align with broader EU sustainability initiatives like the Energy Performance of Buildings Directive, integrating product-level data into building-level assessments. The regulation represents a significant shift for the construction sector’s digitalisation and sustainability efforts, to enable more informed choices based on both performance and environmental impact. 

Reports and Disclosures 

UK Sustainability Reporting Standards – UK SRS 

The International Sustainability Standards Board (ISSB) was established at COP26 in 2021 as part of the IFRS Foundation to create a global baseline for sustainability reporting. The UK government, a strong supporter of the ISSB, has established a framework to assess these standards for endorsement in the UK. If approved, this would become the first UK Sustainability Reporting Standards. The government plans to consult on exposure drafts of UK SRS in Quarter 1 2025, as part of a wider Sustainability Disclosure Reporting framework led by HM Treasury. 

Following the creation of the standards and subject to endorsement, the Financial Conduct Authority will be able to introduce requirements for UK-listed companies to report sustainability-related information to investors. The government has also committed to consulting on requirements for economically significant companies to disclose information using future UK SRS. 

Streamlined Energy and Carbon Reporting – SECR 

The UK’s Streamlined Energy and Carbon Reporting (SECR) policy, introduced in 2019, establishes mandatory carbon and energy reporting requirements for a wide range of organisations. The policy applies to quoted companies (those listed on major exchanges including the London Stock Exchange, EEA markets, NYSE or NASDAQ), large unquoted companies, LLPs, and academy trusts. For unquoted companies and LLPs, the qualification criteria include meeting at least two of the following thresholds: turnover of £36 million or more, balance sheet assets of £18 million or more, or 250 or more employees. 

Companies that consume less than 40,000 kWh of energy in a reporting period qualify as low energy users and are exempt from SECR requirements. Whilst quoted companies must report global data, large unquoted companies, LLPs and academy trusts are only required to report UK energy usage. The policy also includes a ‘comply or explain’ provision allowing organisations to omit data if collection is not possible, provided they explain what has been excluded and why. This provision gives organisations in earlier stages of their ESG reporting journey time to develop more comprehensive reporting capabilities for future years. 

Your Responsibilities 

Next Steps with Below280 

The regulatory landscape is shifting. Below280 specialises in exactly the services organisations need right now — LCA, EPD certification, and CBAM compliance. Our extensive experience in Life Cycle Assessments makes us one of the longest-established UK consultancies in this field, offering ISO 14040/44 compliant assessments and Environmental Product Declarations, along with carbon capture due diligence. This expertise is particularly valuable for businesses needing to address specific now mandated climate impact assessment requirements. 

Our capabilities extend to providing Carbon Border Adjustment Mechanism support, comprehensive carbon reporting covering all Scope 1, 2 and 3 emissions, and developing bespoke carbon reduction and Net-Zero plans that align with the UK Government’s procurement policy. By leveraging our multidisciplinary expertise, we support clients throughout their sustainability journey, from initial concept through to the implementation of low carbon systems and infrastructure. 

Conclusion 

In summary, key EU mechanisms have been modified with higher thresholds and streamlined requirements for corporations and international traders, whilst updated regulations now explicitly incorporate climate considerations into planning and construction. Simultaneously, new reporting frameworks are being developed continue to provide structure for carbon and energy reporting. 

These developments signal the UK’s commitment to balancing ambitious sustainability goals with practical implementation challenges. For businesses, 2025 represents a critical preparation period to adapt to these evolving requirements, with particular focus needed on supply chain transparency, carbon reduction strategies, and comprehensive ESG reporting capabilities. 

Not sure which regulations apply to your business?

CBAM, EPD, Part Z, CSRD — the regulatory landscape is moving fast. Below280 helps UK manufacturers understand exactly what applies to them and what they need to do about it.


Global commercial consultancy • Horizon Europe, UKRI & Innovate UK research partner. Specialists in openLCA, and UK openLCA partner for GreenDelta.

Join our mailing list to find out about the things we do, the articles we publish, and anything we find particularly interesting!

Below280
Privacy Overview

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping our team to understand which sections of the website you find most interesting and useful.